How NH Property Tax Bills Are Paid: July and December
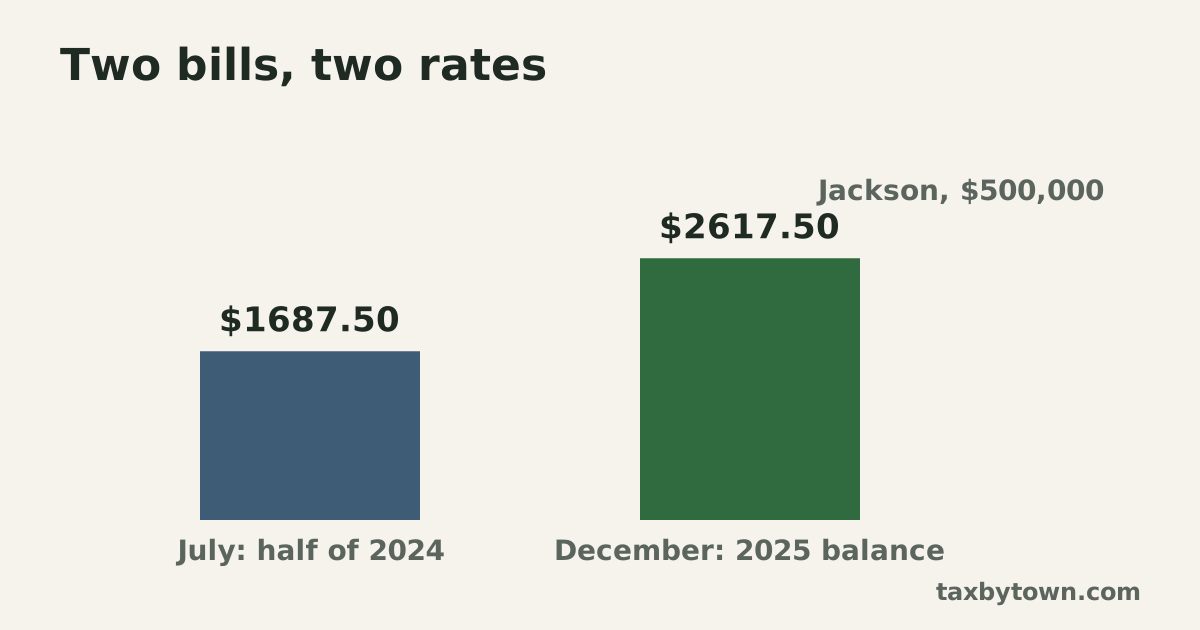
Most New Hampshire towns bill twice a year, and the two bills are calculated differently. The tax year starts on April 1 (RSA 76:2), but the rate for that year is not set until the autumn, so the first bill has to be an estimate.
The July bill
Under RSA 76:15-a: Under semiannual billing the first bill is the "prior year's assessed valuation times 1/2 of the previous year's tax rate", mailed by June 15 and due July 1; the rest of the year's tax is due December 1. In other words it is half of last year's tax.
The December bill
Once the DRA sets the new rate, the town bills the full year's tax and subtracts what was paid in July. That second bill's mailing date is the notice of tax that starts the appeal clock.
Worked example: Jackson
Jackson publishes a $500,000 example. The 2024 rate was $6.75, so the full 2024 tax was $3,375.00, and the July 2025 bill is half: $1,687.50. The 2025 rate came in at $8.61, so the full year's tax is $4,305.00 and the December bill is the balance:
| Amount | |
|---|---|
| Full 2025 tax ($500,000 ÷ 1,000 × $8.61) | $4,305.00 |
| Less July bill | $1,687.50 |
| December bill | $2,617.50 |
Because Jackson's rate rose $1.86, the whole increase lands on the December bill: it is $930.00 larger than the July one. In a town whose rate fell, the December bill is the smaller of the two. Jackson's water precinct, where it applies, is billed on top.
Other schedules
Some towns bill annually, some quarterly and some on an optional fiscal year; RSA 76:1-a sets which bill counts as the notice of tax under each. The town page for any municipality shows its 2024 and 2025 rates, and the calculator shows the July half for any assessed value.
Sources
- RSA 76:15-a, Semi-Annual Collection of Taxes; RSA 76:1-a, Notice of Tax.
- Town of Jackson, 2025 property tax rate information, read 2026-10-20.
- NH Department of Revenue Administration, 2025 Municipal Tax Rates (completed as of January 23, 2026): DRA.
Questions
Why is my July tax bill half of last year's?
Under semiannual billing the first bill is the "prior year's assessed valuation times 1/2 of the previous year's tax rate", mailed by June 15 and due July 1; the rest of the year's tax is due December 1. (RSA 76:15-a).
What does the December bill cover?
The full year's tax at the new rate, less the July payment. On Jackson's published $500,000 example that is $4,305.00 − $1,687.50 = $2,617.50.